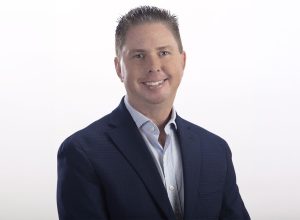


Buyers of commercial property insurance have been trained, mostly by the market itself, to shop on price. The submission goes out, three or four numbers come back, and the cheapest one wins unless something obvious is wrong with it. That process works well for simple risks, but it falls apart on complex property, where the product a buyer is purchasing is not a premium but a promise about what happens when a loss hits. Dave Nickelson-Rueschhoff, Vice President and National Complex Property Practice Leader at OneDigital, draws a hard line between the two outputs. “A quote is a number on a piece of paper. It tells a client what someone is willing to charge them today for their exposures based on its unique risk profile,” he says. “A solution is something completely different. It anticipates how the risk will behave, where the gaps sit, and what happens when a claim happens.” That distinction is not semantic. It determines whether a company discovers the limits of its insurance program during a renewal conversation or during a catastrophe.
The Submission Is Not The Business
The standard brokerage workflow treats the submission as the starting point. Schedule of values, loss runs, construction details, occupancy codes, all sent out the door. The document becomes a proxy for the company, and whatever the markets return is shaped entirely by what fits inside it. Nickelson-Rueschhoff inverts the sequence. “A solution starts with understanding the business, not just the submission,” he says. “Before I approach any market, I want to know how the client operates, where their exposures are concentrated, and what their risk profile looks like in practice.”
The consequence of that ordering runs further than it first appears. “That understanding is what shapes the ask, and the ask is what determines the quality of what comes back,” he says. Underwriters are not generating pricing in a vacuum; they are responding to a framing. A broker who has not understood how the business runs cannot frame anything, so the ask defaults to the generic, and the generic gets priced defensively. The client then interprets the resulting number as a verdict on their risk when it is really a verdict on how the risk was presented. Buyers who want better outcomes should be interrogating how well their broker can describe the operation before they ever look at a quote sheet. If the broker cannot explain where the exposure resides, the market will not hear a story worth pricing favorably.
The Coverage Nobody Asked About
Every property program has a perimeter, and the most expensive thing about that perimeter is that few examine it until something lands outside it. Clients renew what they bought last year. Brokers quote what the client asked for. The conversation stays inside the lines of the expiring program, and the gaps survive another 12 months because nobody is paid to go looking for them. Nickelson-Rueschhoff treats that search as core to the work rather than an upsell. “Look for the coverage the client has not specifically asked about,” he says. “Some of the most valuable conversations I have had involve coverages a client does not currently purchase.”
The payoff is structural, not incremental. “Identifying those gaps removes the potential for an uninsured claim, which is the moment when the difference between a quote and a solution becomes very clear and very real,” he says. An uninsured claim is a category of loss distinct from a large one. A large covered loss is a financial event the program was designed to absorb. An uninsured loss is a direct hit to the balance sheet with no transfer mechanism behind it, and the discovery happens at the worst possible moment, when the adjuster is already on site. Measured against that, a few basis points of premium savings on a renewal is a rounding error. The discipline here is uncomfortable for brokers because it means raising coverages the client did not budget for and may decline. It is also the only part of the process that addresses risk the buyer does not know they are carrying.
Relationships Over Portals
Technology has made the easy end of the market efficient. Rating engines handle straightforward property risks faster and cheaper than any human could, and that is a genuine improvement. The error is assuming the same machinery scales upward. Complex property, catastrophe-exposed, hard-to-place, structurally unusual, does not resolve into inputs a portal can score. “Carrier relationships do the work a rating portal cannot,” Nickelson-Rueschhoff says. “Complex property risks need someone who can tell the story to the right underwriter and negotiate terms with both credibility and insight.”
What makes that advocacy effective is knowing what the other side needs. Nickelson-Rueschhoff spent more than 25 years in property and casualty across underwriting, catastrophe modeling, product management, and broking, which he describes as giving him a view of the risk from both sides of the table. “Years spent underwriting these accounts means I know what a market needs to see,” he says, “and that changes the outcomes on hard-to-place risks.” That is a concrete claim about where value is created in the chain. The underwriter is making a judgment under uncertainty, and the quality of that judgment depends on the quality and framing of the information in front of them. A broker who has sat in the underwriting seat knows which details move the decision, and which are noise. One who has not is submitting paperwork and hoping. On accounts nobody wants to write, that difference is frequently the difference between terms and a declination.
The tension across all three points is the same. Price is legible and immediate; program quality is neither, until a claim makes it so. “Anyone can bring back a price,” Nickelson-Rueschhoff says. “Building the right program takes a different level of engagement.” Risk managers who evaluate brokers purely on the number they return are, in effect, selecting for the cheapest version of the work rather than the best version of the coverage. The bill for that choice arrives later, and it does not arrive as a premium.
Follow Dave Nickelson-Rueschhoff on LinkedIn for more insights on complex property risk, program design, and the state of the property insurance market.